
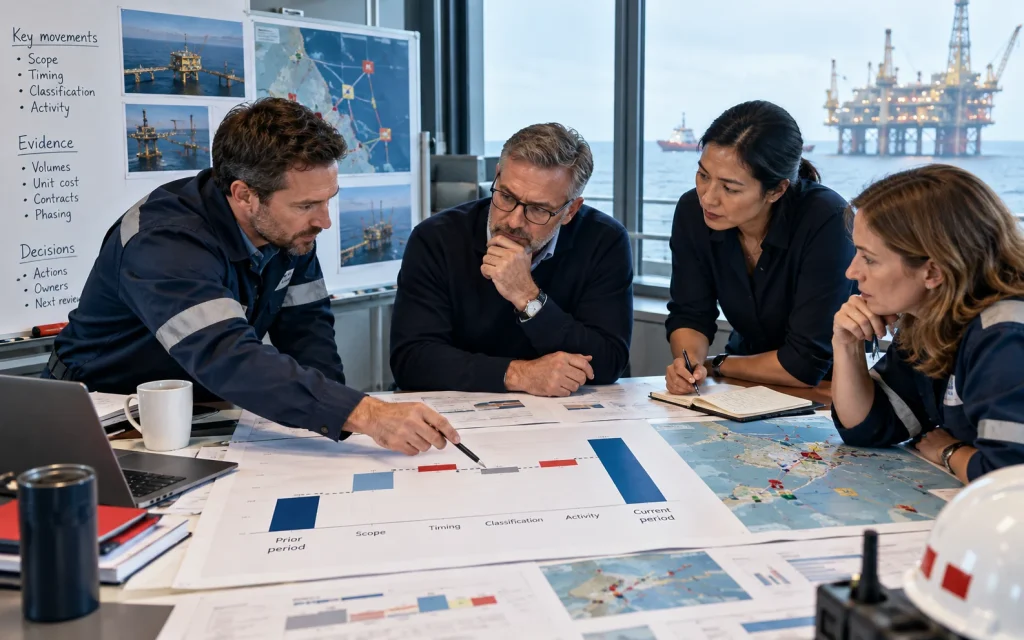
A variance bridge explains how one financial position became another. For a CFO, its value is the separation of drivers: scope, timing, classification and activity should not be collapsed into a single unexplained change.
The bridge does not need elaborate graphics to be useful. It needs a consistent comparison, arithmetic that reconciles, and explanations someone can trace to the accepted source records.
Define the starting and ending positions
State the periods, properties, ownership basis and expense definition. If the portfolio changed, identify that first. A bridge that starts with one set of properties and ends with another needs a visible population step.
Agree on the sign convention. Favorable and unfavorable labels should follow the measure: a lower expense and a lower revenue do not have the same implication.
Separate drivers without double counting
In a fictional example, monthly operating expense increases from $200,000 to $235,000. Newly included properties account for $15,000, timing explains $8,000, and additional activity explains $12,000. The steps total the $35,000 movement.
Each amount needs support. If an invoice belongs to both a new property and a timing issue, decide which bridge step owns it. Counting it twice makes the explanation look complete while the arithmetic is wrong.
Label unresolved amounts
Leave a clearly named unresolved step when evidence is incomplete. That is more useful than forcing every difference into a plausible category. Assign the unresolved amount to a reviewer and a date.
Avoid disguising a balance as other without a follow up plan. The CFO should know which parts of the explanation are accepted and which could still change.
Connect the bridge to the operating response
Different drivers imply different work. A scope change needs a comparable population view. Timing needs a period explanation. Classification needs an agreed mapping decision. Recurring activity may need an operating response.
Keep the bridge with the reporting definition so next month’s review can reproduce it. Upstream+ LOS and budget detail can support the investigation; the team still owns the interpretation and acceptance of the explanation.
A useful bridge turns a total into a set of responsibilities the organization can act on.
Research and references
These sources offer background for the review question. The worked examples and review methods above are Upstream’s practical guidance.
- Cost Estimating and Assessment GuideU.S. Government Accountability Office · GAO-20-195G · 2020 · Authoritative government guide
Cost-management reference; apply its general principles to your project scope.
- A review of dashboards in performance management: Implications for design and researchYigitbasioglu & Velcu · International Journal of Accounting Information Systems · 2012 · Peer-reviewed literature review
Research perspective on dashboard design and drill-down.
Common questions
Does every bridge step need evidence?
Every material explanation should point to an accepted record or review. Label unsupported amounts as unresolved.
How do I prevent double counting?
Assign each underlying difference to one bridge step and reconcile the steps to the total movement.
Put the question to work
Explore the connected workflow for leadership or bring your well data question to a working session.