
Cash month and activity month answer different questions. A cash oriented view follows the timing defined by the financial records. An activity period view follows the period assigned to the underlying production or work. A comparison is only meaningful when that basis is consistent.
A February repair may reach a later accounting period. Production from one month may be reported or settled in another. The movement on a monthly statement can therefore reflect timing as well as operations.
Name the basis in the review
Put the basis beside the date range. Define which source field determines the period and how adjustments are handled. Do not assume everyone uses the words cash, accounting and activity in exactly the same way.
This is a reporting definition exercise. The accounting treatment remains governed by your organization’s policies and the underlying records.
Match the question to the timeline
For a field performance question, the team needs the period in which the operating activity occurred. For a financial period review, it needs the accepted accounting scope. For a cash question, it needs the relevant cash timing and measures.
Comparing one basis this month with another basis last month can manufacture a trend. It can also make a genuine operating change disappear.
Build a small timing bridge
Suppose a fictional $12,000 service job was performed in February and appears in an April financial review. A useful note connects the service period, posting period and property. It tells the operating team that April’s expense movement includes earlier work.
The note does not erase the April financial movement. It explains why the activity timeline and the financial timeline differ.
Carry corrections forward visibly
When records are revised, preserve the accepted explanation and identify the affected periods. Recheck any saved view or presentation that depends on the corrected scope. A copied screenshot does not automatically update when the underlying record changes.
Upstream+ exposes Activity and Accounting views in the demonstrated LOS workflow. Use that distinction to frame the question, then confirm the specific source and period definitions with the people responsible for the record.
Agreement on dates often resolves a disagreement that initially looks like an argument about performance.
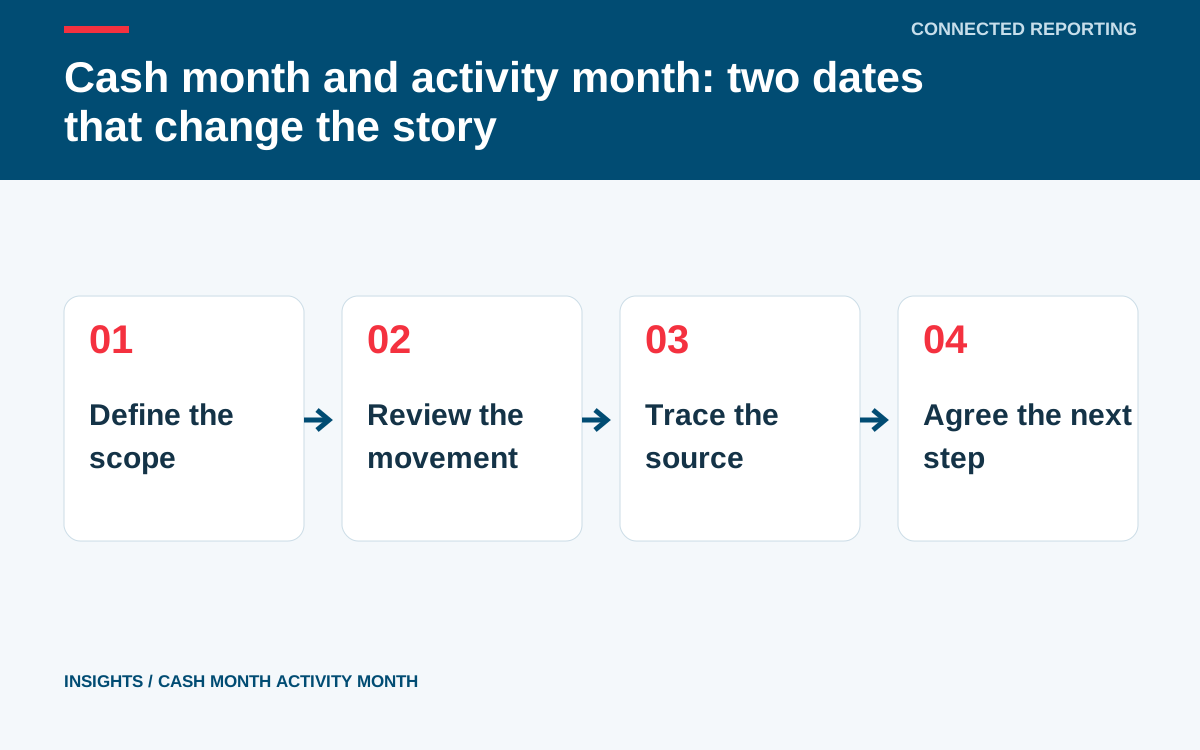
Research and references
These sources offer background for the review question. The worked examples and review methods above are Upstream’s practical guidance.
- Beyond Accuracy: What Data Quality Means to Data ConsumersWang & Strong · Journal of Management Information Systems · 1996 · Peer-reviewed research
Research perspective on evaluating data quality beyond accuracy.
- A review of dashboards in performance management: Implications for design and researchYigitbasioglu & Velcu · International Journal of Accounting Information Systems · 2012 · Peer-reviewed literature review
Research perspective on dashboard design and drill-down.
Common questions
Which basis is always better?
Neither is universally better. Select the basis that answers the review question and state its definition.
Why can expense move without new field work?
Posting or settlement timing, adjustments and classification can change the financial period view.
Put the question to work
Explore the connected workflow for los & loe or bring your well data question to a working session.